Inclusive Branches 📍️ Branch Map
Налаштування доступності Скинути
Розмір шрифту Аа Аа Аа
Колірна схема: Звичайна Біло-чорна Чорно-біла Бежева
Зробіть кілька простих кроків, і ми вже з вами на зв'язку!
1. Завантажте додаток WordCraft для свого пристрою та пройдіть реєстрацію.
2. Відскануйте QR-код через додаток WordCraft (відкривши «Налаштування»), і дзвінок з перекладачем та представником компанії почнеться автоматично.

Medical Insurance

For teams of 10 or more employees

Take care of your team's health.
A healthy team is an effective team

image

ARSENAL IC
A care service for team health

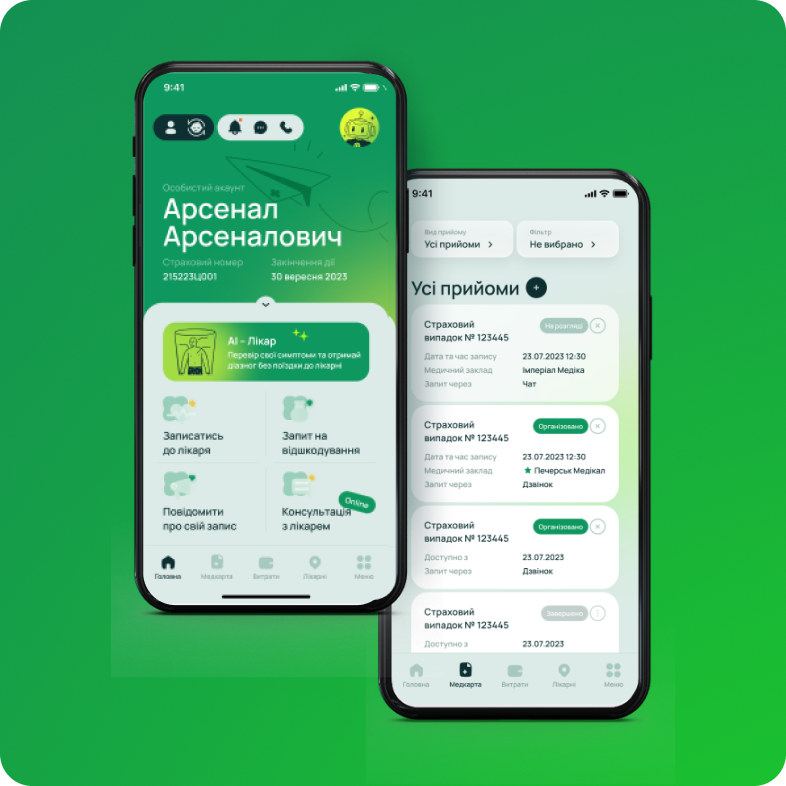
Our mobile app, powered by medical AI, makes treatment faster than ever.

Who is it for?

Teams of 10 employees or more,
plus their family members

What's covered?

The coverage plan will be tailored
to your team's specific needs

Medical Insurance — Right in Your Smartphone

Order Medical Insurance
Arsenal
Fill out the form below, and our manager will get in touch with you during business hours.
By clicking "Submit," you agree to the processing of your personal data in accordance with our Privacy Policy
Arsenal

What the service includes

Mobile App
Arsenal IC

  • AI doctor that diagnoses with 87% accuracy
  • Quick doctor appointment booking
  • All medical facilities on the map
  • Book an online consultation
  • Your entire medical history in one place
  • Convenient management of your child's insurance
  • Submit claims for reimbursement

Your Personal
Arsenal Assistance

  • We pick up fast
  • Multiple phone lines plus a dedicated ambulance hotline
  • We'll quickly book your doctor's appointment and order medication
  • Available via Viber, Telegram, and email
  • Booked an appointment? We'll remind you via SMS
  • We operate continuously during blackouts

We cover the following medical services:

advantage.text

Emergency ambulance

advantage.text

Doctor house calls
or office visits

advantage.text

Dentistry

advantage.text

Outpatient clinic treatment

advantage.text

Health check-ups

advantage.text

Medication delivery to your home

+  Much more

What determines the cost of insurance?

The number of people on your team
The health condition of your team members
The level of medical facilities where your team will receive care
Whether a deductible applies
Your team's field of activity
The program's selected coverage options

How to contact our doctors?

Emergency assistance

Email for inquiries to Arsenal Assistance

All medical facilities
and pharmacies we work with

+

Object of Insurance

The object of insurance is the life, health, and working capacity of the Insured Person.

+

Insured Risks

The insured risk under the insurance contract is the risk of making an insurance payout to the Policyholder (or another person specified in the insurance contract or by law) in accordance with the terms of the insurance contract and/or legislation, by reimbursing expenses incurred for the Insured Person to receive medical care, medical and/or other services of a defined list and quality, within the scope provided for by the insurance contract, or by paying for the cost of such services, as a result of the occurrence of an event against which the insurance is taken out (the insured risk), including the Insured Person's illness, exacerbation of a chronic illness, a health disorder resulting from an accident, other health disorders and/or events provided for by the insurance contract.

+

Territory of Coverage Under the Insurance Contract

Ukraine (with the exception of: settlements where Ukrainian state authorities are temporarily unable to exercise their powers, settlements located along the line of contact, the territory of the Autonomous Republic of Crimea and the city of Sevastopol, temporarily occupied settlements, and areas of active combat).

+

Term of the Insurance Contract

The minimum and maximum term of the insurance contract is from 1 to 365 or 366 calendar days (depending on the number of calendar days in the year), or another term by agreement of the parties. The term of the insurance contract is set by agreement of the parties.

+

Minimum and Maximum Insured Amount (Liability Limit), If the Minimum and Maximum Insured Amount Is Determined by the Terms of the Insurance Product

No minimum or maximum insured amount (liability limit) is defined by the insurance product. The insured amount under the insurance contract is determined by agreement of the parties. A separate insured amount is set for each Insured Person. The insured amount is set in Ukrainian hryvnias and is aggregate (after an insurance payout is made, the insured amount decreases by the amount of that payout).

+

Minimum and Maximum Insurance Premium and/or Rate

The minimum and maximum annual insurance rate ranges from 0.1% to 60.0% of the insured amount. The insurance premium for each Insured Person is determined under the insurance contract by multiplying the insured amount by the insurance rate set by the Insurer for the relevant Insured Person. The insurance premium under the insurance contract equals the sum of the insurance premiums for each Insured Person specified under the contract. No minimum or maximum insurance premium is set (it depends on the insured amount agreed upon by the parties).

+

Type and Minimum/Maximum Amount of Deductible (If Applicable)

The insurance contract may establish a deductible for individual types of services and/or insurance options. Type of deductible: flat (the insurance payout for each insured event is reduced by the deductible amount). The deductible amount is chosen by the Policyholder and specified in the insurance contract as a percentage of the insurance payout, unless otherwise agreed by the parties in the insurance contract. No minimum or maximum deductible amount is defined by the insurance product.

+

Procedure for the Insurance Contract Coming Into Effect

The insurance contract comes into effect on the start date of its term.

+

Insurance Period

Insurance periods are established for each Insured Person or under the insurance contract by agreement of the parties.

+

Insurance Restrictions (If Applicable)

The following cannot be an object of insurance:

  • The life, health, or working capacity of persons who have been declared legally incapacitated under the law.
  • Indirect losses and non-material damage.

+

Procedure for the Insurance Contract Coming Into Effect

Terms for making insurance payouts:

  • Payment timeframe: the payout is made within 10 business days of the date the Insurance Act is drawn up.
  • Form of payout: cash or bank transfer, as specified in the Payout Application.
  • Method of payout: by paying for the services or medications provided through the Assistance service, or directly to the consumer if the services were paid for independently and the requirements of the contract are met.
  • Payout decision: made within 10 business days of receiving the application and all required documents. The decision is formalized in an Insurance Act.
  • Documents required for payout:
    • Application for the insurance payout.
    • A certified photocopy of the passport (or a certificate from the Unified State Register).
    • A certified photocopy of the taxpayer ID number (RNOKPP).
    • Birth certificate (for persons under 16).
    • The original extract from the outpatient/inpatient medical record.
    • Original prescriptions or medical documents.
    • Original invoices and receipts from healthcare facilities.
    • A photocopy of the license to provide medical services, if the services were provided by a private individual.
  • Document submission deadline: the application and documents must be submitted within 30 calendar days of the date the services were paid for, or after the insurance contract terminates.
  • Timeframe issues: if documents are submitted after the deadline, the insurer may refuse the payout.

Procedure for calculating and the amount of the insurance payout:

  • Payout for medical services paid for independently:
    • Medications: 100% of expenses reimbursed, within the option's limit, unless otherwise specified by the Insurance Coverage Program (ICP).
    • Services not exceeding the cost of equivalent services at Contracted Healthcare Facilities: 100% of expenses reimbursed, within the option's limit.
    • Services exceeding the cost of equivalent services at Contracted Healthcare Facilities: reimbursement of the portion of expenses equal to the cost of equivalent services at Contracted Healthcare Facilities, within the option's limit.
    • A service not available at a Contracted Healthcare Facility: the payout amount is determined based on the cost of an equivalent service at a healthcare facility of the corresponding category, per the Insurer's/Assistance's list.
  • Reduction of the insured amount: after each insurance payout, the insured amount is reduced by the amount of that payout.
  • Maximum payout amount: the total amount of payouts may not exceed the insured amount or the option's limit (if applicable). The payout may not exceed the amount of direct loss caused by the insured event.
  • Expenses after the contract ends: the Insurer does not reimburse expenses incurred after the contract's term expires or is terminated early, except for emergency inpatient treatment begun during the term of the contract. In this case, expenses are reimbursed for up to 10 calendar days after the contract ends.
  • Corporate limit: if the ICP provides for a corporate limit, the total amount of payouts under an option/set of options may not exceed that corporate limit.
  • Deferral of decision: the Insurer has the right to defer its decision on recognizing an event as insured and making a payout, or to refuse a payout, within the timeframes and in the cases provided for by the insurance contract.

+

Possible Consequences for the Consumer in Case of Failure to Fulfill Obligations Under the Insurance Contract, Including Late Notification of an Insured Event Without Valid Reasons and Late Payment of the Insurance Premium or Its Subsequent Installment

  • Late notification of an insured event without valid reasons, or failure to fulfill other obligations set out in the insurance contract or by law, if this makes it impossible for the Insurer to establish the fact, causes, and circumstances of the insured event or the amount of the harm caused, is grounds for the Insurer to refuse the insurance payout.
  • The occurrence of an event during a period for which the insurance payment was not paid in the amount and within the timeframe specified in the insurance contract is grounds for the Insurer to refuse the insurance payout.
  • Failure by the Policyholder to pay the next installment of the insurance premium within the timeframe specified in the insurance contract (if the premium is paid in installments) is grounds for early termination of the insurance contract and its loss of validity (under the terms provided for in the contract).

+

Information on the Possibility of Purchasing the Insurance Product Separately, If Such Product Is Offered Together With an Ancillary and/or Additional Good, Work, or Service That Is Not Insurance-Related, as a Component of a Single Package or Contract

The insurance contract is not ancillary to any other goods, works, or services that are not insurance-related.

+

Terms for Obtaining a Discount on the Insurance Product and the Insurer's Promotional Offers (If Any), Including Their Validity Periods

No discounts are provided for this insurance product. There are no promotional offers.

+

List of Information That Is Material to Assessing the Insured Risk, and/or Information About Other Circumstances Taken Into Account When Determining the Insurance Premium

Terms of the Insurance Contract chosen by the Policyholder: the insured amount; the list of insured risks; the term of the Insurance Contract; the territory of coverage; the terms for paying the insurance premium; the terms of the chosen Insurance Coverage Program (ICP); the terms for making insurance payouts; the list of Healthcare Facilities for arranging medical care; the list of diseases, medical conditions, services, medications, and medical products that are exclusions from coverage; whether deductibles apply; and whether limits/sublimits on the Insurer's liability apply to individual ICP options.

Individual characteristics of the object of insurance necessary for assessing the insured risk: the number of Insured Persons under the Insurance Contract; the Insured Person's age; the Insured Person's type of professional activity; the Insured Person's participation in any sports (professional or amateur); the Insured Person's participation in any activity involving increased danger to life and/or health; the presence/absence of chronic or disabling illnesses; the presence/absence of hereditary diseases or congenital defects; a history of regular inpatient treatment more than once a year.

Other information material to assessing the insured risk: information about prior insurance and loss history for the previous insurance period; information about other active insurance contracts regarding the object of insurance.

Information about the Policyholder's insurance needs and requirements, as specified in the Insurance Application submitted by the Policyholder.

The following are considered changes in circumstances material to assessing the insured risk (determining the probability and likelihood of an insured event occurring and the amount of possible losses) and/or other circumstances affecting the amount of the insurance premium under the Insurance Contract and/or materially affecting the terms of the Insurance Contract: the Insured Person being declared legally incapacitated under the procedure established by law; an assessment of the person's daily functioning being conducted by an expert assessment team, under the procedure established by law, for the purpose of determining disability status (or a medical-social assessment of a child being conducted, under the procedure established by law, for the purpose of determining a child's disability status); being registered at a narcological, psychoneurological, or other dispensary; having AIDS or being infected with HIV; being assigned a disability status of any group for any reason (or the category "child with a disability" or "child with a disability, subgroup A"); developing a mental illness or cancer; a change in occupation; taking up any sports (professional or amateur); participation in any activity involving increased danger to life and/or health; the existence of insured events under prior insurance with other insurers that were not reported in writing when the Insurance Contract was concluded; the presence/detection of chronic diseases; the presence/detection of hereditary diseases or congenital defects.

+

Consumer Notice on the Need to Review, Prior to Concluding the Insurance Contract, Information About Exclusions From Insured Events and Grounds for Refusal to Make Insurance Payouts, the Insurer's Liability Limits for a Specific Object of Insurance, Insured Risk, and/or Insured Event, as Well as the Procedure for Calculating and the Terms for Making Insurance Payouts, Including a Reference to Such Information

Before concluding the insurance contract, the consumer needs to review the following information:

  • exclusions from insured events and grounds for refusal to make insurance payouts,
  • the Insurer's liability limits for a specific object of insurance, insured risk, and/or insured event,
  • the procedure for calculating and the terms for making insurance payouts.

This information can be found in the General Terms of the Insurance Product, available here, and in the Insurance Product Information Document, available here.

+

Procedure and Terms for the Provision of Services

Before concluding the insurance contract, the Insurer (insurance intermediary), based on information received from the client, determines the client's insurance needs and requirements. If the client requires individual advice, the Insurer (insurance intermediary) provides such advice upon the client's request. This individual advice is provided free of charge. Before concluding the insurance contract, the Insurer (insurance intermediary) provides the client with accessible and comprehensive information about the insurance product, about the insurer, and about the insurance intermediary (if the insurance product is sold through an insurance intermediary). The insurance contract is concluded in writing. The insurance contract may be executed in paper form or as an electronic document.

+

Cost, Price/Rates, and Fee Amount (Interest, Commissions) for the Insurance Product

Under the insurance contract, the Policyholder pays an insurance premium. The insurance contract does not provide for any other payments besides the insurance premium (such as interest, commissions, etc.). The insurance premium is calculated based on information provided by the Policyholder when concluding the insurance contract. The insurance premium is calculated within the minimum and maximum insurance premium and/or insurance rate specified above for this insurance product.

+

Total Amount of Expenses, Including Fees, Payments, and Other Costs the Consumer Must Pay in Connection With Receiving the Financial Service, Including Taxes, or, If the Specific Amount Cannot Be Determined, the Procedure for Determining Such Expenses

When concluding the insurance contract, the Policyholder pays only the insurance premium provided for by the insurance contract. In accordance with subparagraph 165.1.27 of paragraph 165.1 of Article 165 of the Tax Code of Ukraine, the following income is not included in a taxpayer's total monthly (annual) taxable income: the amount of an insurance payout, insurance compensation, or surrender value received by the taxpayer under an insurance contract from a resident insurer, other than long-term life insurance (including lifetime pension insurance) and non-state pension provision, provided the following conditions are met: a) for life or health insurance of the taxpayer, in the case of: the insured person surviving to the date or event specified in the life insurance contract, or reaching the age specified in such contract; the surrender value, to the extent it does not exceed the sum of insurance payments made under a life insurance contract other than long-term life insurance; in the event of an insured event — the fact that harm was caused to the insured person must be duly confirmed. If the insured person dies, the insurance payout due to beneficiaries or heirs is taxed according to the rules and rates established for inheritance taxation (a beneficiary is treated as an heir for this purpose); b) for property insurance, the amount of insurance compensation may not exceed the value of the insured property, determined at market prices as of the date the insurance contract was concluded, increased by the amount of insurance payments (contributions, premiums) paid; c) for civil liability insurance, the amount of insurance compensation may not exceed the amount of harm actually caused to the beneficiary, as determined at market prices as of the date of such insurance payout. Provided the above conditions are met, no taxes or fees are payable by the Policyholder as a result of receiving the financial service.

+

Consumer's Right of Withdrawal, Right to Terminate or Cancel the Contract, Right of Early Performance, and the Procedure and Consequences of Exercising Such Rights

The insurance contract terminates and loses validity by agreement of the parties to the contract, as well as in the event of:

  • the expiration of the contract's term;

  • the Insurer having fulfilled all obligations to the Policyholder;

  • non-payment/late payment of the next installment of the insurance premium;

  • liquidation of the Insurer, liquidation of a Policyholder that is a legal entity, or the death of a Policyholder who is an individual (except as provided for by the Law of Ukraine "On Insurance");

  • a court decision declaring the insurance contract invalid entering into legal force;

  • other cases provided for by Ukrainian legislation and the insurance contract.

  • Either party must notify the other party in writing (electronic form) of its intent to terminate the insurance contract early no later than 30 calendar days before the termination date.

  • In the event of early termination of the insurance contract at the request of the Policyholder or the Insurer due to the Policyholder's failure to comply with the terms of the contract, the Insurer refunds the insurance premium paid for the remaining period of the contract, minus expenses directly related to concluding and performing the contract, and any insurance payouts already made under the contract.

  • In the event of early termination of the insurance contract at the Insurer's request, or on the Policyholder's initiative due to the Insurer's violation of the contract's terms, the Policyholder is refunded the full insurance premium paid.

  • Expenses directly related to concluding and performing the insurance contract are deducted in the amount corresponding to the share of such expenses specified in the insurance contract.

  • The Insurer refunds the paid insurance premium (or a portion thereof) within 10 business days of the contract's termination date, to the Policyholder's bank account or by another means via payment systems.

  • If there are unresolved insured events at the time of early termination, the Insurer refunds the insurance premium (or a portion thereof) after such events are settled.

  • If the Policyholder is included on a list of persons associated with terrorist activity or subject to international and/or other sanctions, the refund of the insurance premium (or a portion thereof) occurs after the Policyholder is removed from such list.

  • The paid insurance premium is not refunded in the event of early termination of the insurance contract due to the Insurer having fully performed its obligations to the Policyholder.

The Policyholder has the right, within 30 calendar days of concluding the insurance contract, to withdraw from the contract without giving a reason (if the contract's term exceeds 30 calendar days and no notifications of events bearing the characteristics of an insured event have been made under the contract).

  • The Insurer refunds the paid insurance premium (or a portion thereof) within 10 business days of receiving the Policyholder's notice of withdrawal, to the Policyholder's bank account or by another means via payment systems.

+

Procedure for Amending the Insurance Contract

The insurance contract does not provide for unilateral amendment of its terms.

Amendments to the insurance contract are made by mutual written consent of the Parties. Amendments are made by concluding additional contracts/additional agreements to the insurance contract.

A Party that considers it necessary to amend the terms of the insurance contract sends a proposal to that effect to the other Party, in accordance with the terms of the insurance contract.

If the Parties fail to reach agreement on amending the terms of the insurance contract, it continues to be in effect on its previously agreed terms, or it may be terminated early by the Parties.

+

Availability and Procedure for Handling Complaints and Out-of-Court Dispute Resolution

When providing insurance services to Consumers, PJSC "ARSENAL INSURANCE" complies with all applicable consumer protection legislation, cares about its Consumers' rights, and is committed to resolving issues raised by consumers.

PJSC "ARSENAL INSURANCE" also considers it important, at every stage of reviewing an inquiry, to inform Consumers of their rights, and to note that PJSC "ARSENAL INSURANCE" reviews client inquiries (proposals, comments, applications, complaints) from both legal entities and individuals in accordance with current Ukrainian legislation and the Procedure for Interaction with Consumers and Handling Inquiries (across all channels) approved by PJSC "ARSENAL INSURANCE."

A client has the right, either personally or through an authorized representative, to submit (send) inquiries to PJSC "ARSENAL INSURANCE" concerning the activities of the company and/or its employees.

Consumers have free access to information about insurance services published on the PJSC "ARSENAL INSURANCE" website at: https://arsenal-ic.ua/, as well as at service locations.

Any issues that arise for a client are resolved as follows:

  1. Out of court, through a verbal or written inquiry sent to the email address [email protected], sent or submitted directly to the company's registered address: 154 Borshchahivska St., Kyiv, 03056, Ukraine, or reported by phone at 0-800-60-44-53. To protect the rights of the Policyholder as a consumer of insurance services, PJSC "ARSENAL INSURANCE" has established a dedicated competent commission to review applications, comments, proposals, and complaints, located at 154 Borshchahivska St., Kyiv, 03056, tel. 0-800-60-44-53, email [email protected]. Such inquiries, which must be submitted in writing, are reviewed within the procedure and timeframes established by the Laws of Ukraine "On Consumer Protection" and "On Citizens' Appeals."

  2. If the Consumer disagrees with the decision made regarding their inquiry/complaint/claim, they may appeal such decision by contacting the Regulator — through the official website of the National Bank of Ukraine: https://bank.gov.ua/ua/consumer-protection; correspondence and written inquiries address: 9 Instytutska St., Kyiv, 01601, tel. 0 800 505 240, email: [email protected], website: https://bank.gov.ua/.

  3. In certain disputed cases, the matter may also be resolved through the courts. In accordance with Part One of Article 4 of the Civil Procedure Code of Ukraine, every person has the right, in the manner established by this Code, to apply to the court for the protection of their violated, unrecognized, or disputed rights, freedoms, or legitimate interests.

All disputes arising between the Policyholder and the Insurer under concluded insurance contracts are resolved through negotiation, and if no agreement is reached, in accordance with the procedure established by current Ukrainian legislation.

+

Availability of Guarantee Funds or Compensation Schemes Applied in Accordance With Legislation

PJSC "ARSENAL INSURANCE" maintains a guarantee fund; no compensation schemes are available.

Order Medical Insurance
Arsenal
Fill out the form below, and our manager will get in touch with you during business hours.
By clicking "Submit," you agree to the processing of your personal data in accordance with our Privacy Policy
Arsenal

Why Us?

01

 icon (15)

№1 in the CASCO Market

02

icon (8)

10 Million UAH in Payouts Daily

03

icon (7)

Payout speed from 3 Days

04

icon (16)

Recommended by our clients to their friends

05

icon (6) 2

Company with 100% Ukrainian capital

06

icon (20)

20 Years in the Ukrainian market

07

icon (6) 4 (2)

350,000 Clients

08

icon (6) 4 (3)

93% Client Satisfaction Rate

Got any questions?
Get in touch with us in a convenient way

Message us

What Our Clients Say

Вчора звернулась, щоб записатись до лікаря. Обробили звернення швидко, оператор був дуже чемний і допоміг підібрати зручний час. Все пройшло легко і без зайвих питань. Дуже задоволена сервісом!

Зверталась до контакт-центру два дні тому, потрібно було терміново записатись до лікаря. Дуже приємно вразила оперативність — за кілька хвилин все оформили, запропонували зручний час і навіть нагадали про візит. Спілкування було максимально комфортним, без зайвих пояснень і затримок. Дякую за турботу та людяне ставлення!

Гарна комунікація, швидке і просте вирішення проблем.

Супер професійне відношення. Та дуже швидко реагують і допомогають

Все на найвищому рівні. Вже не раз були страхові випадки, завжди швидко і без питань їх виплачували.

Солідно виглядають. Персонал професійний. Ставлення привітне.

Користуюсь послугами цієї страхової компанії 8 років. Завжди швидко виконують всі умови договору, навіть за умов, коли ситуація вийшла за умови договора, виплатили все в повному об'ємі.

Гарне обслуговування - надійність і швидкість вирішення питань. Дякую )