Скинути




 Eng
 Українська
 Русский


Motor hull insurance against theft. What you need to know
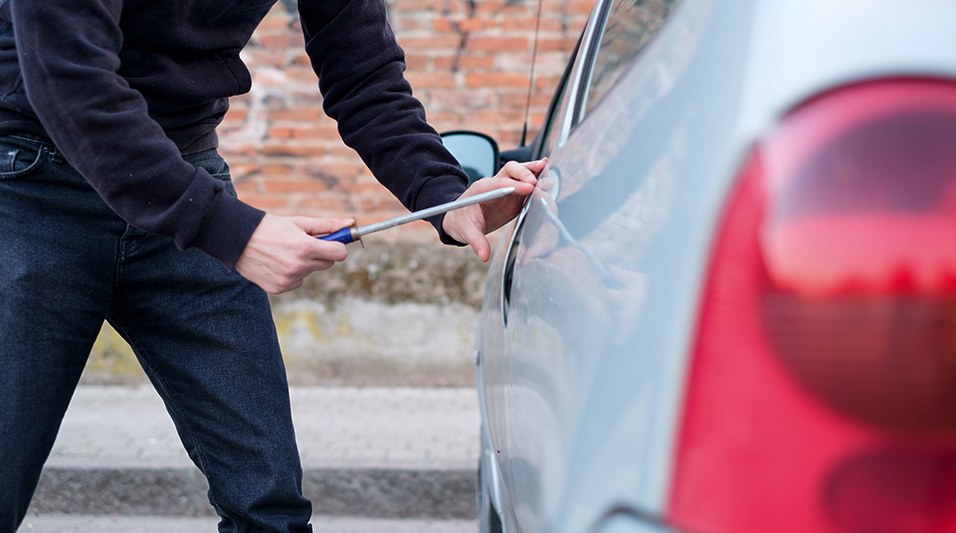
Benish GPS, a company specialising in the installation and maintenance of vehicle security systems, provides statistics on car thefts in Ukraine by brand and region. According to the research, since the beginning of 2020, criminals have tried to steal every fifth Toyota car. The second and third places in the ranking were taken by BMW and Mercedes-Benz. In the regional context, the sad leaders were Kyiv, Kharkiv, and Odesa.
The CASCO policy protects against theft and illegal actions of third parties, and allows you to receive compensation if you find only tyre tracks instead of your car in the morning.
What is CASCO?
Full hull insurance is a voluntary type of insurance that protects a car from any damage. The list of risks includes road accidents, theft, damage to the car as a result of natural disasters, illegal actions of third parties, and the complete destruction of the car.
CASCO insurance does not complement the voluntary MTPL insurance policy. It provides protection against the risks of your car. The insurance is valid throughout Ukraine, regardless of the place of purchase.
When concluding a contract, it is important to pay attention to the amount of insurance coverage. It should be equivalent to the cost of the car. You should study the exclusions, the cases in which the insurer will not compensate for the loss. The contract may specify a deductible, i.e. the amount that the insurance company does not reimburse. It is calculated as a percentage of the cost or in cash. Many insurance companies issue motor hull insurance without a deductible.
A policy with a full range of options is expensive. Not all owners need to cover all possible events that lead to damage or loss of a car. The most common option for partial voluntary car insurance is hull insurance against theft and road accidents.
Let's analyse motor hull insurance in case of theft or theft
Policy principle: if the car owner's vehicle is stolen, the insurer pays the amount specified in the hull insurance contract, which is equal to the full cost of the car. The insurance company deducts depreciation from this amount.
The concepts of "theft" and "embezzlement" are not identical. The first term, from the point of view of lawyers, means that the vehicle was taken over against the will of the driver, but was not used afterwards. Theft means theft for the purpose of resale or transfer to third parties. In case of theft without financial gain, it is easier to find the car. It may be abandoned somewhere, so the price of insurance for the risk of theft is lower than for theft. When concluding a contract, you need to find out how your insurer interprets these concepts.
The calculation of the cost of a policy with the risk of theft differs from the standard algorithm. Age and driving experience are not taken into account. Priority is given to the presence of a car alarm system. It is assessed whether a particular make/model is on the list of the most stolen cars in the insured's region of residence.
The cost of hull insurance with the risks of theft and road traffic accident varies from one insurance company to another, averaging 1-5% of the market price. This is significantly less than the damage caused by theft. Statistics show that stolen cars are rarely recovered. Insurance protects against the risk of losing a car and covers losses.
How not to be denied a claim
The hull insurance contract operates according to certain rules. If the insured violates them, the company may refuse to pay out. A common reason for such a decision is failure to provide all the necessary items and documents. Among them:
- car registration certificate;
- sets of keys to the doors and ignition;
- sets of anti-theft system controls.
Upon the occurrence of an insured event, you must immediately notify the police. The Interception plan announced promptly can return the car. The second call is to the insurance company. Make sure it is recorded.
While waiting for a representative of the insurance company, it is advisable to interview witnesses, if any, write down their contact details, and write a statement about the theft to the police. The reimbursement procedure starts after the criminal case is initiated. The terms and procedure for compensation are specified in the contract.
A lawful refusal to pay occurs in the following cases:
- the insured breaches the terms of the contract;
- misrepresentation of information about the event;
- car theft due to the owner's negligence. He did not switch on the alarm, forgot to close the lock;
- violation of the vehicle storage rules;
- fraud (when the theft was initiated by the driver, the owner of the car);
- missing the deadline for contacting the insurance company, failure to submit a full package of documents and items;
- inaccurate information about the installed anti-theft equipment.
You can avoid a negative decision by following simple rules. If the second set of keys is lost, it is better to notify the insurer before the theft. The STS should not be left in the glove compartment. Do not transfer the keys to third parties.
The CASCO policy does not prevent car theft. It reimburses financial losses to the owner. The driver should reduce the risks of car theft himself. To do this, you need to park in guarded car parks and install an anti-theft device recommended by the manufacturer. Car colour is a matter of personal preference, but insurance company statistics show that brightly coloured cars are stolen less often than cars of calm, subtle colours.
Different vehicle owners often make the same mistake. When signing an agreement, they do not read the text and do not clarify the details. A clear understanding of the essence of the insured event and knowledge of the procedure and payment terms will help to avoid conflict situations and receive compensation in the predicted amount.