Скинути




 Eng
 Українська
 Русский


Apartment flood insurance: what you need to know
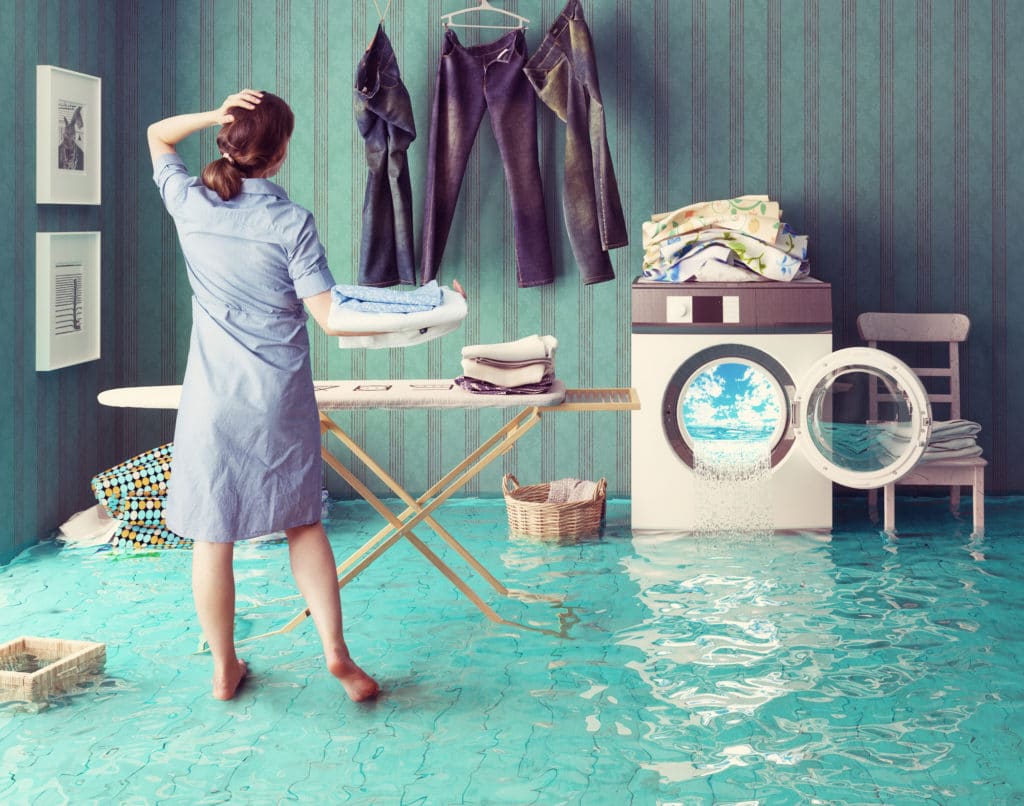
Home is the place where people want to feel safe the most. It is here that you find a so-called safe haven where you can have a good rest, relax after a hard day's work, and play with your children. The worst thing is when the peace is disturbed by some unforeseen circumstances - fires, flooding, etc. Such problems are further complicated by the fact that you will have to pay a tidy sum for the restoration of property and repairs. Home insurance programmes are a reliable mechanism of financial protection against such events. Let's take a closer look at this.
Briefly about property insurance
Unfortunately, people living in high-rise buildings can never be completely sure of the safety of their homes. There will always be a neighbour who may sometimes not turn off the gas tap or turn on the water while filling the bathtub and forget about it.
And we shouldn't forget about burglars. Owners of private homes are not immune from the actions of the latter. In any home, you cannot be completely sure that sewer or water pipes will not break. If such problems arise, you can restore your lost property or repair your home at the expense of the insurance company.
A signed contract will help you get compensation if one of the following events occurs:
- fire
- gas explosion
- theft
- break-in and damage to property;
- flooding, etc.
Companies offer options for insuring your own apartment or liability. In the latter case, the neighbours will receive compensation if the policyholder is to blame for the pipe break and flooding. It is also possible to take out a policy for rented accommodation, which will greatly facilitate relations with the landlord.
What to look for when signing a contract
Statistics show that flooding is one of the most common insured events in city apartments. In this case, the insured items may include utilities, large household appliances, valuables, furniture, and expensive finishes (e.g., laminate, parquet, wallpaper). This list should be discussed with the company's representatives when concluding the contract and checked to ensure that it is recorded in the document. Most often, insurance companies will ask you to take photographs of the objects and indicate their market value at the time of the contract.
It is advised to pay due attention to compiling such a list. On the one hand, this is a rather painstaking task, but on the other hand, it helps to avoid disputes if an insured event occurs and the amount of compensation is calculated.
It is worth asking the manager of a company about items that are not insured. Any contract will contain a list of exclusions. As a rule, the following items are not subject to insurance: cash, electronics (laptop, camera, mobile phone), securities, paintings, jewellery, and exclusive clothing.
This is because money and securities are usually kept in a bank. And to insure antiques, jewellery or paintings, you first need to evaluate them, issue a certificate stating their value, and ensure proper protection. If these items are damaged as a result of flooding, compensation will be paid only if law enforcement agencies can document that the client did not commit fraudulent acts to intentionally damage them.
Separately from flooding, the interior decoration of the premises may be insured, which, in addition to plastering and painting works, traditionally includes: 1) the condition of surfaces finished with plastic, wood, veneer, wallpaper and other materials; 2) built-in furniture or its elements.
Finishes are most often damaged by water, and it is therefore advisable to take care of their restoration in advance.
Steps to take to get compensation
Often, when an apartment or house begins to flood, the owner is too worried and does not always know what to do to receive full compensation. In order to avoid problems with payments in the future, the following steps must be taken
- report the incident to the insurance company within 24 hours. The phone numbers are listed in the policy, and they are also available on the official website;
- call the emergency service that serves the building. If you don't have the necessary contacts at hand, you can check with the insurer's representative to find out exactly where to call. In some situations, the police will need to arrive;
- take measures to reduce the damage - for example, to block the burst riser, collect water from the floor, etc. However, it is advisable not to move large items until the insurance expert has inspected the premises;
- prepare to show evidence of your non-involvement in the flood. These may include documents confirming regular maintenance of communications or a plumber's report on the causes of the emergency.
And finally, every insured should remember that if the owner's negligence is simple forgetfulness, for example, they left the water on in the bathroom, they can't expect compensation. But when the pipes burst due to a poor connection or because their service life has been exceeded, payments will be made.